
Why Customer Concentration Is a Hidden Business Risk
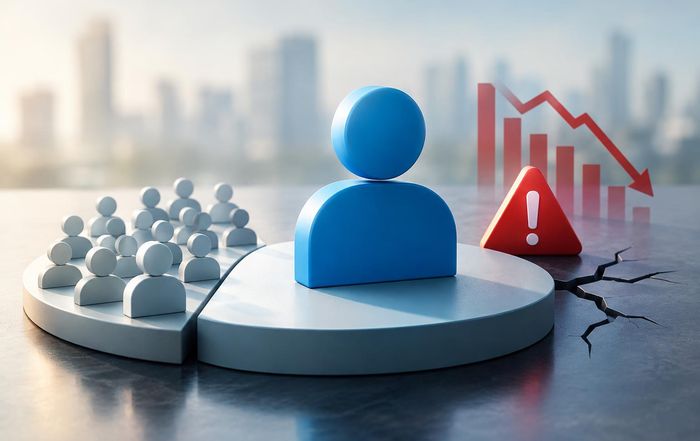
A business can look healthy on paper and still carry a fragile revenue base. That fragility often comes from customer concentration: when too much of a company's sales depend on one client, a handful of clients, or a single channel partner. The risk is easy to overlook because concentration can feel like proof of product-market fit, especially in the early stages of a company's growth. A big customer can validate the offer, stabilize cash flow, and help a founder scale faster. Yet the same relationship can become a structural weakness if pricing power shifts, a contract is lost, or the customer's own business changes direction.
This issue matters across industries, from software and manufacturing to logistics, marketing services, and industrial supply chains. It is especially relevant for firms that report strong headline growth while quietly relying on a small number of accounts. Investors, lenders, and acquirers tend to care about this more than many operators do, because concentration changes the quality of revenue, not just the amount. For more context on how revenue quality fits into business strategy, it helps to look at related content on business fundamentals, investment, and economy.
Why concentration can be more dangerous than it first appears
Customer concentration is often hidden because it does not always show up in the same way as debt or margin pressure. A company may report rising sales, healthy gross profit, and strong operating momentum while still depending on a single buyer for a disproportionate share of revenue. That creates a subtle asymmetry: the business may appear diversified from the outside, but internally it is exposed to a small set of decisions it cannot control. If one customer renegotiates terms, delays orders, or decides to switch suppliers, the effect can be immediate and severe.
The risk is amplified when the concentrated customer is also the most demanding. Large buyers often request lower pricing, longer payment terms, custom features, or operational concessions that smaller customers would never command. That can compress margins and distort priorities, because the supplier begins optimizing around the needs of one account rather than building a durable market position. In sectors shaped by procurement power, this dynamic can be particularly pronounced, which is why business leaders often watch developments in banking, stock markets, and global trade conditions to understand how demand concentration affects financing and valuation.
The warning signs are usually visible before the damage is done
Concentration risk rarely appears without clues. One common sign is when a company's revenue grows faster than its customer base. Another is when management repeatedly highlights a major account as a growth engine while offering limited detail on diversification. In public markets, investors often scrutinize annual reports and risk disclosures for customer dependence, but private companies can be even more exposed because the concentration may be known only to founders, finance teams, and a few senior managers. That makes internal reporting especially important.
There are also operational clues. Sales teams may spend most of their time servicing one or two enterprise accounts. Product roadmaps may be shaped by a single buyer's requests. Procurement, staffing, and inventory decisions may become tied to the forecast of one customer rather than to a broader market. When that happens, the business is not just concentrated in revenue; it is concentrated in behavior. In many cases, the company also becomes vulnerable to payment delays, which can strain working capital and create knock-on pressure in banking relationships or short-term financing arrangements.
Why founders and operators underestimate the risk
Founders often see concentration as a temporary stage rather than a structural issue. At first, that assumption can be reasonable. Landing a large anchor customer can fund hiring, improve unit economics, and create proof points that help win additional business. The problem is that many companies never fully exit that stage. Instead, they become comfortable with a revenue mix that is efficient in the short run but brittle in the long run. The customer becomes not just a client, but a pillar of the company's forecast, headcount plan, and valuation narrative.
There is also a psychological bias at work. A strong relationship with a major customer can create a false sense of security, especially if the client has stayed loyal for years. Teams may assume that because the relationship has been stable, it will remain stable. But customer behavior changes for reasons that have nothing to do with the supplier's quality: mergers, leadership turnover, budget cuts, strategic pivots, regulatory shifts, or internal restructuring can all alter purchasing decisions. For founders thinking about long-term resilience, this is where founders, innovation, and marketing intersect with risk management rather than growth alone.
The financial consequences can spread far beyond lost revenue
When a major customer leaves, the first effect is obvious: sales decline. The secondary effects are often worse. Fixed costs remain, so margins can compress quickly. If the company had hired ahead of demand, payroll becomes harder to support. If it had invested in equipment, software, or inventory to serve the large customer, those assets may be underutilized. If the lost account had favorable payment behavior, working capital may deteriorate as receivables become less predictable. A single customer loss can therefore trigger a broader operational reset.
This is one reason lenders and investors often discount concentrated revenue streams. A business that relies heavily on one customer may deserve a lower valuation multiple than a more diversified peer, even if current earnings look similar. That is especially true in cyclical sectors, where concentration can coincide with broader demand weakness. A company exposed to one buyer, one industry, or one geography may appear resilient until a downturn hits. For readers tracking how these pressures affect capital allocation, the dynamics overlap with employment, stock markets, and broader economy trends.
Not all concentration is equally risky
Some concentration is manageable, and in certain businesses it is even rational. Specialized suppliers, contract manufacturers, and niche software vendors may naturally work with a small number of large customers. The real question is not whether concentration exists, but whether the relationship is balanced, transferable, and strategically defensible. A company that serves a few major customers across different industries may be less vulnerable than one tied to a single sector or a single procurement decision maker. Likewise, a supplier with switching costs, proprietary technology, or long-term contracts may have more protection than one selling a commoditized product.
What matters most is whether the concentration is deliberate and monitored. If a company chooses to serve a small number of high-value clients, it should understand the trade-off and keep contingency plans in place. That means tracking renewal risk, contract terms, customer health, and the revenue share of each account. It also means avoiding overreliance on one channel partner or one platform, because channel concentration can be just as dangerous as direct customer concentration. In technology-heavy businesses, this often overlaps with artificial intelligence, technology, and crypto ecosystems where platform dependence can change quickly.
What good risk management looks like in practice
The first step is measurement. Leadership teams should know the share of revenue from the top customer, top five customers, top ten customers, and top channel partners. They should also track gross margin by account, payment terms, renewal dates, and contract concentration by geography or product line. This is not just a finance exercise. Sales, operations, and executive teams need the same visibility so they can plan around exposure before it becomes a crisis. Companies that build this discipline early are often better positioned to navigate shifting demand in global markets and industry-specific downturns.
The second step is diversification, but not in a superficial sense. Winning more customers is not enough if all of them come from the same industry, the same region, or the same buying pattern. Real diversification means broadening the customer mix in a way that reduces correlated risk. That may require new segments, new geographies, new distribution channels, or new product packaging. It can also mean refusing growth that is too dependent on one account, even when that account is tempting. For businesses in transition, sustainable growth is often more valuable than fast but brittle growth.
The third step is contractual and operational protection. Longer notice periods, minimum purchase commitments, diversified supplier relationships, and clear service-level terms can all reduce exposure. Companies should also stress-test their forecasts against the loss of their largest customer and ask what would happen to staffing, cash flow, and debt service. That kind of scenario planning is especially important when financing conditions tighten or when the broader market becomes less forgiving, as can happen during shifts in banking or investment sentiment.
Why investors and acquirers care so much
For outside stakeholders, customer concentration is often a proxy for hidden fragility. Investors may worry that a business has limited bargaining power, poor diversification, or weak demand visibility. Acquirers may see concentration as a diligence issue because they do not want to inherit a revenue base that could evaporate after a transaction. Even when a concentrated customer relationship is stable, it can still complicate valuation because the future is harder to underwrite. The question is not simply whether the customer is profitable today, but whether the company would remain viable if the relationship changed.
That is why concentration risk often shows up in deal discussions, credit analysis, and earnings commentary. It can affect financing terms, acquisition multiples, and strategic planning. It can also shape how a business is perceived in the market, especially if it is trying to position itself as a scaled platform rather than a dependent supplier. A company with strong diversification tends to be easier to understand, easier to finance, and easier to scale. A company with concentrated customers may still be attractive, but it must usually prove that the risk is manageable rather than merely hope it stays invisible.
Customer concentration is hidden not because it is rare, but because it can coexist with growth and profitability for a long time. That makes it one of the more deceptive business risks: easy to ignore when revenue is rising, difficult to fix when a major customer pulls back. The companies that handle it best are usually the ones that treat concentration as a strategic metric, not just a sales statistic.